VA Loan Buyers
VA Loan Realtor San Diego
You earned your VA home loan benefit. I'll make sure you use it to win the right home, with $0 down, no PMI, and an offer sellers take seriously.
The VA loan is one of the most powerful home buying tools in the country, and in a market as competitive as San Diego, it matters who's writing your offer.
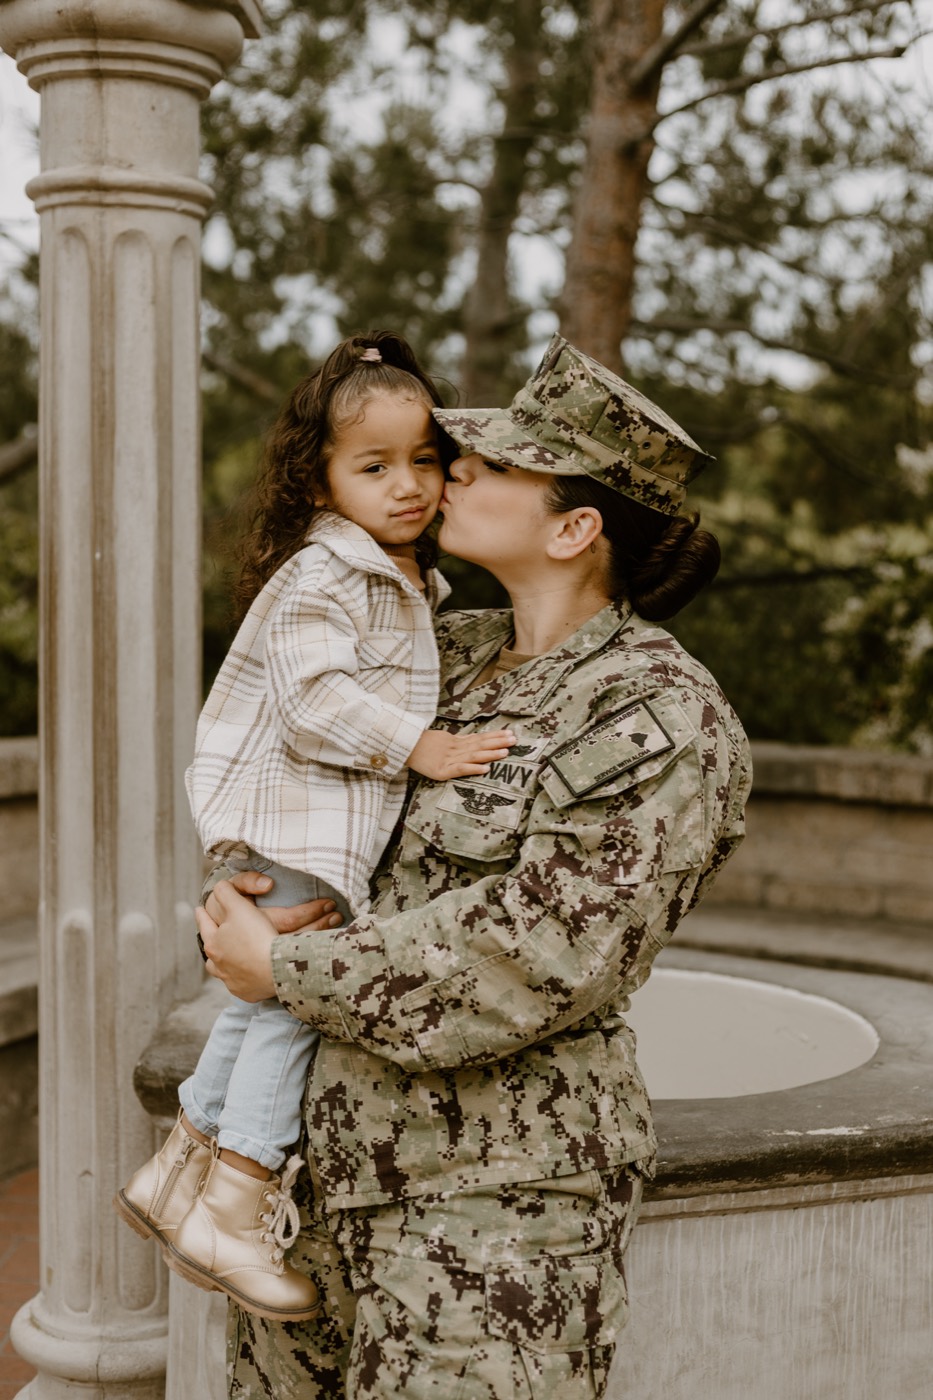
As a U.S. Navy Veteran, I've been on your side of the table. As a VA loan realtor in San Diego, I know how to put that benefit to work: from finding homes that will pass the VA appraisal to negotiating seller credits that cover your closing costs.
Why VA buyers choose a VA loan realtor
- $0 down payment for eligible buyers with full entitlement, with no VA loan limit in that case.
- No private mortgage insurance (PMI), which can save hundreds per month compared with a low-down conventional loan.
- Competitive interest rates and flexible credit guidelines set by VA-approved lenders.
- Seller concessions: VA rules allow sellers to contribute toward your closing costs and certain other expenses.
- Funding fee exemption for many veterans receiving VA disability compensation.
How I help VA buyers win in San Diego
1. Get the right pre-approval
I'll connect you with experienced, VA-savvy local lenders who close on time, because a fast, reliable lender is part of what makes a VA offer strong. You'll get your Certificate of Eligibility (COE) and a clear picture of your budget, including how BAH fits in.
2. Target homes that fit VA guidelines
VA appraisals include Minimum Property Requirements (MPRs) for safety, soundness and sanitation. I screen listings for red flags like peeling paint on older homes, roof issues or missing handrails so you don't fall in love with a home that can't close.
3. Write an offer that competes
Some sellers still have outdated ideas about VA loans. I present your offer with a strong lender letter, a clear timeline and terms that protect you, and I call the listing agent to explain why a VA buyer is a safe bet.
4. Negotiate, inspect and close
From inspections and repairs to appraisal questions and final walk-through, I stay with you through closing day, even if you're still overseas or on deployment.
"You don't need to know everything about VA loans. You need someone in your corner who does."
VA loan buyer checklist
- Request your Certificate of Eligibility (your lender can usually pull it for you).
- Get pre-approved with a VA-experienced lender.
- Decide your must-haves: commute, schools, bedrooms, yard, garage.
- Tour homes in person or by live video.
- Make an offer, inspect, appraise, and close.
Want more detail on funding fees, entitlement and California-specific veteran benefits? Read my VA loan benefits in California guide, or see whether an assumable VA loan could get you a lower rate.
VA loan FAQs
Can I use my VA loan more than once?
Is there a VA loan limit in San Diego?
Do VA loans take longer to close?
Can a spouse use a VA loan?
VA loan eligibility, entitlement, funding fees and terms are determined by the U.S. Department of Veterans Affairs and your lender. This page is educational and is not lending advice.